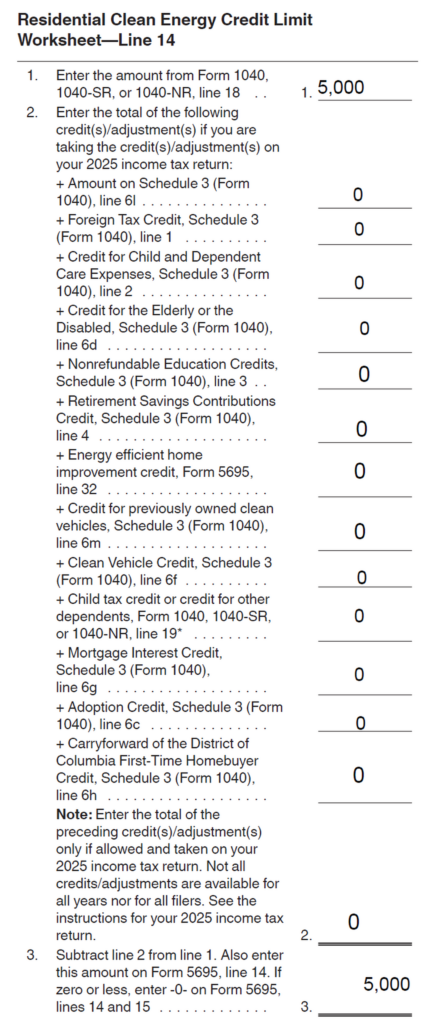
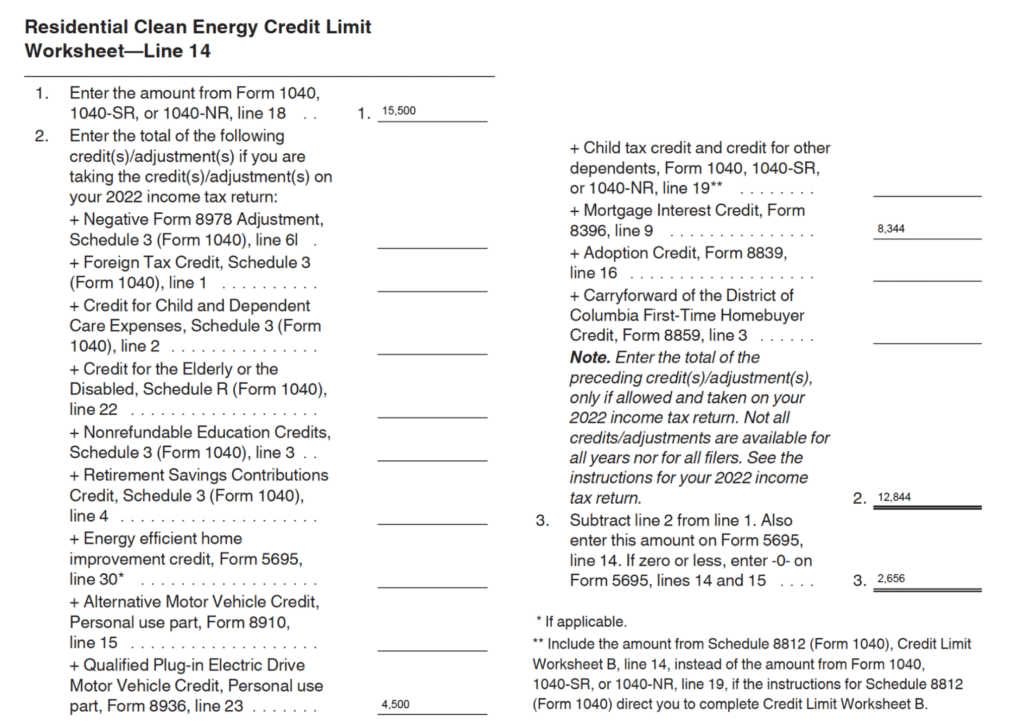
The residential clean energy credit limit worksheet helps a homeowner figure out the maximum Residential Clean Energy Credit they can claim for a qualifying project. It is the form-following calculation tool that turns eligible costs into the allowable credit amount for the return. To use it correctly, you need the qualified property cost, the credit rate for the tax year, and any limits or carryover rules that apply.
What the Worksheet Covers
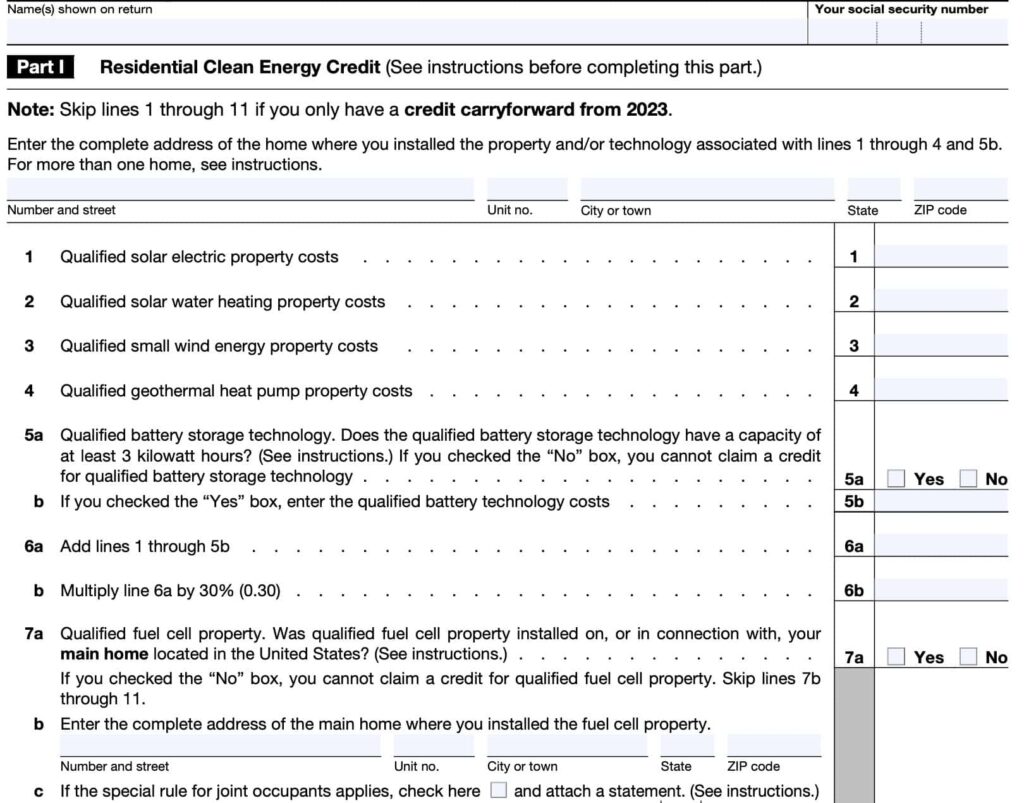
Start with the project costs that count as qualified expenditures. Depending on the tax year and property type, that usually means the installed cost of solar electric property, solar water heating, fuel cell property, small wind energy property, geothermal heat pump property, or battery storage technology that meets the credit rules. The worksheet is not about financing costs or routine repairs; it is built to measure the eligible basis for the credit calculation.
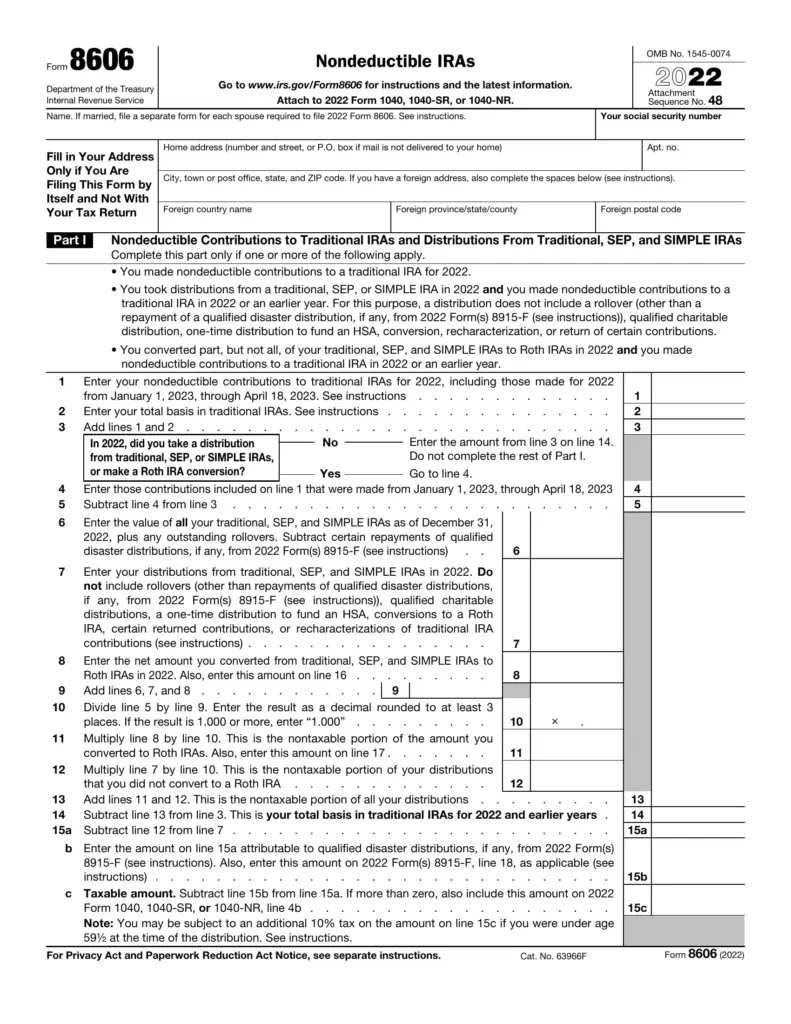
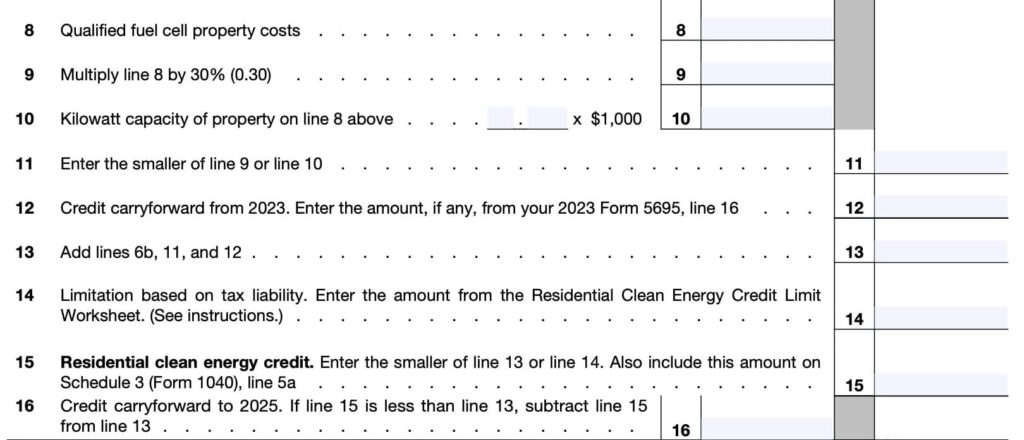
Next, apply the credit percentage and any cap that limits the result. For some projects, the credit is a fixed percentage of qualified costs, while others may have a dollar cap or additional limitation tied to the tax year. If the law allows a carryover, the worksheet also helps keep track of any unused credit that moves to another year. The final number is the allowable credit before it is entered on the return.
How to Finish the Calculation
Work through the worksheet line by line using the figures from your project records and the instructions for that tax year’s form version. Enter the qualified cost amount, multiply by the applicable percentage if required, and then compare the result with any statutory limit. If the worksheet includes a carryforward or coordination step, use that to reduce or preserve the credit as instructed. The goal is to arrive at the exact credit amount the return permits.
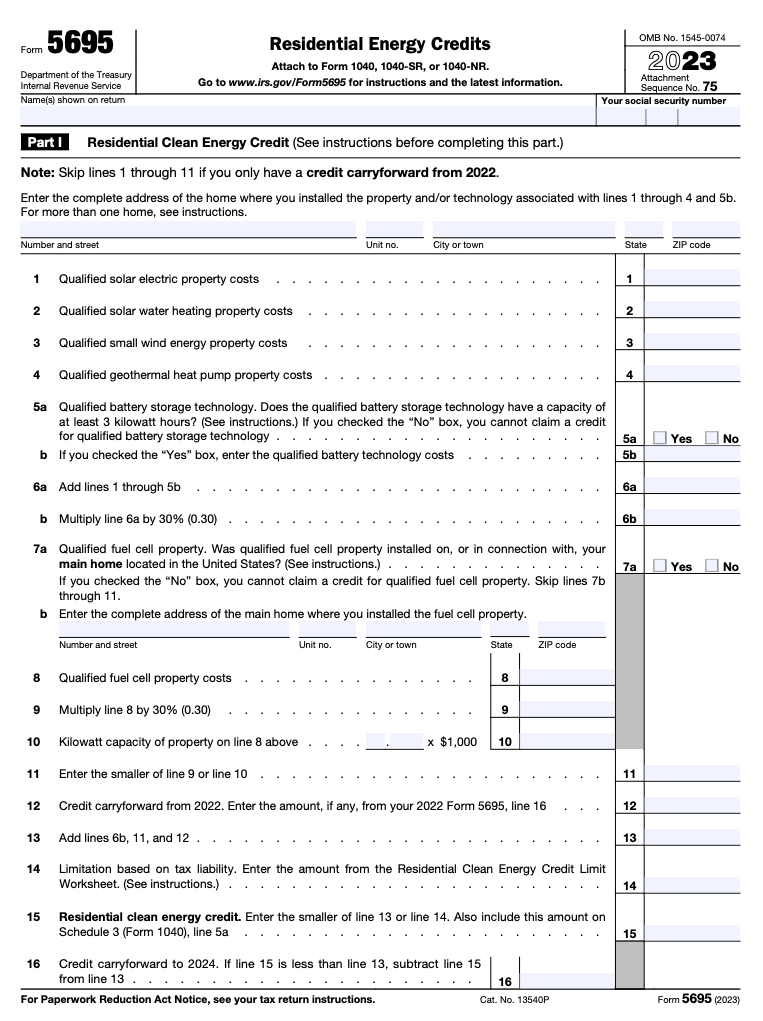
After the worksheet produces the final figure, transfer that result to the residential clean energy credit line on the tax return or the related schedule for that year. Keep the completed worksheet with your tax records in case the IRS asks how you calculated the amount. A careful, line-by-line review is the best way to avoid overstating the credit and to make sure the return reflects the allowable limit exactly.